
Almonty's Sangdong Bet: Contracted Demand Meets a Softening Tungsten Print
Published on 10/12/2026 at 02:51 | Editorial boerse-global.de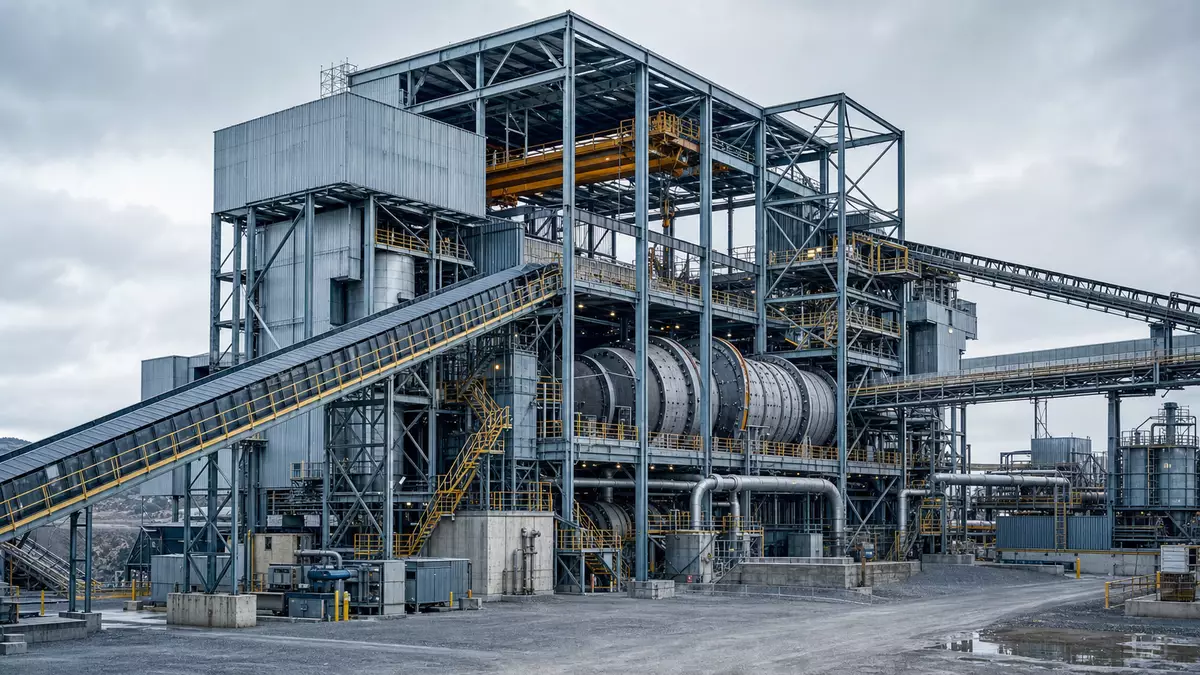
Almonty finds itself caught between two competing narratives. On one side sits a bullish long-term case built on a projected tungsten supply shortfall and a mine finally moving into production. On the other, a freshly printed price decline serves as a reminder that scarcity forecasts do not translate into a straight-line price path.
The stock's 2.7% gain on Friday captures only a sliver of this tension. A single positive session says nothing about whether tungsten prices have stabilized, nor does it confirm that the Sangdong ramp-up is proceeding without friction.
A 21,000-Tonne Gap — and a Price That Fell Anyway
S&P Global published a forecast on Wednesday estimating that tungsten mines outside China will deliver roughly 22,000 tonnes of contained WO3 in 2026. Measured against demand, that leaves a shortfall of approximately 21,000 tonnes. Sangdong is explicitly named as part of the supply-side answer to that deficit.
That projection gives Almonty a substantial backdrop. The mine represents not just a standalone production project but additional supply in a market forecast to be undersupplied. Yet such a forecast describes neither a guaranteed price trajectory nor revenue the company has already booked.
Should investors sell immediately? Or is it worth buying Almonty?
The counterweight arrived Friday. Shanghai Metals Market pegged Rotterdam APT prices at $2,700–$3,100 per mtu, down $100 from a month earlier. Other tungsten reference prices also retreated.
How does a price decline square with an expected supply gap? The two statements operate on different planes. The forecast describes the supply-demand balance outside China; the price report records a market move. Scarcity expectations, in other words, cannot be read as an automatic guarantee that every reference price will rise.
The Contract That Anchors the Story
Beyond the market environment, what matters for Almonty is how securely its output is spoken for. On September 21, the company reported final operating approval for the processing plant at Sangdong. That cleared Phase I for commercial operation and permitted the sale of tungsten concentrate.
This step links industrial development to the ability to actually sell — more than a technical milestone. For investors, it shifts the focus toward execution of the business rather than the mere prospect of a tight commodity.
According to company disclosures, more than 90% of Phase I production is contractually committed to Global Tungsten & Powders for 21 years from first delivery.
That offtake arrangement carries more weight for the investment case than a general reference to tungsten scarcity. It provides a framework for marketing the output. It does not, however, guarantee specific revenues or profits.
Two Risks, Two Different Questions
The pressures described in media reports on Thursday operate on separate levels. A potential decline in the tungsten price concerns the market environment. The risks surrounding the Sangdong ramp-up concern operational execution. The two should be assessed independently: progress at the mine does not automatically dispel concerns about pricing.
Conversely, anxiety over a price pullback is not proof that operational development has deteriorated. The reports describe apprehensions, not a confirmed new disruption at Sangdong. That distinction matters. A possible setback in the commodity market cannot be converted into a concrete production failure.
Almonty at a turning point? This analysis reveals what investors need to know now.
From First Concentrate to a Booked Cargo
The operational backdrop is the first tungsten production at Sangdong, reported roughly two weeks ago. CEO Lewis Black stated that the mine has entered production and ramp-up. Attention now turns to the steps between production start and delivery.
The company has booked the first shipment of concentrate for October 24. That date gives investors a concrete anchor. A booked shipment, though, is not a completed delivery. The date stands for the next announced step, not its already-finished execution.
What emerges is a picture that resists reduction to either the latest share-price move or the worries about tungsten pricing. Production start provides a tangible operational reference point. The execution risks reported in the media show why the ramp-up still warrants attention.
Two separate developments will shape the next phase: the price conditions for tungsten and the execution of the announced delivery. The former concerns the market environment, the latter progress at Sangdong. Friday's gain does not replace that distinction — and the real test is not simply whether tungsten stays scarce, but how Sangdong brings production and contracted offtake together.
Ad
Almonty Stock: New Analysis - 12 October
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.