Almonty's Sangdong Fixes Face a C$43 Million Test as a Canadian Claim Looms
Published on 11/12/2026 at 04:42 | Editorial boerse-global.de
Almonty Industries is asking investors to weigh two very different kinds of risk at once. One is operational and measurable in tonnes per hour. The other is legal and measured in millions of dollars and conversion shares. Neither has yet been resolved, and each will shape how the tungsten producer's growth story is valued.
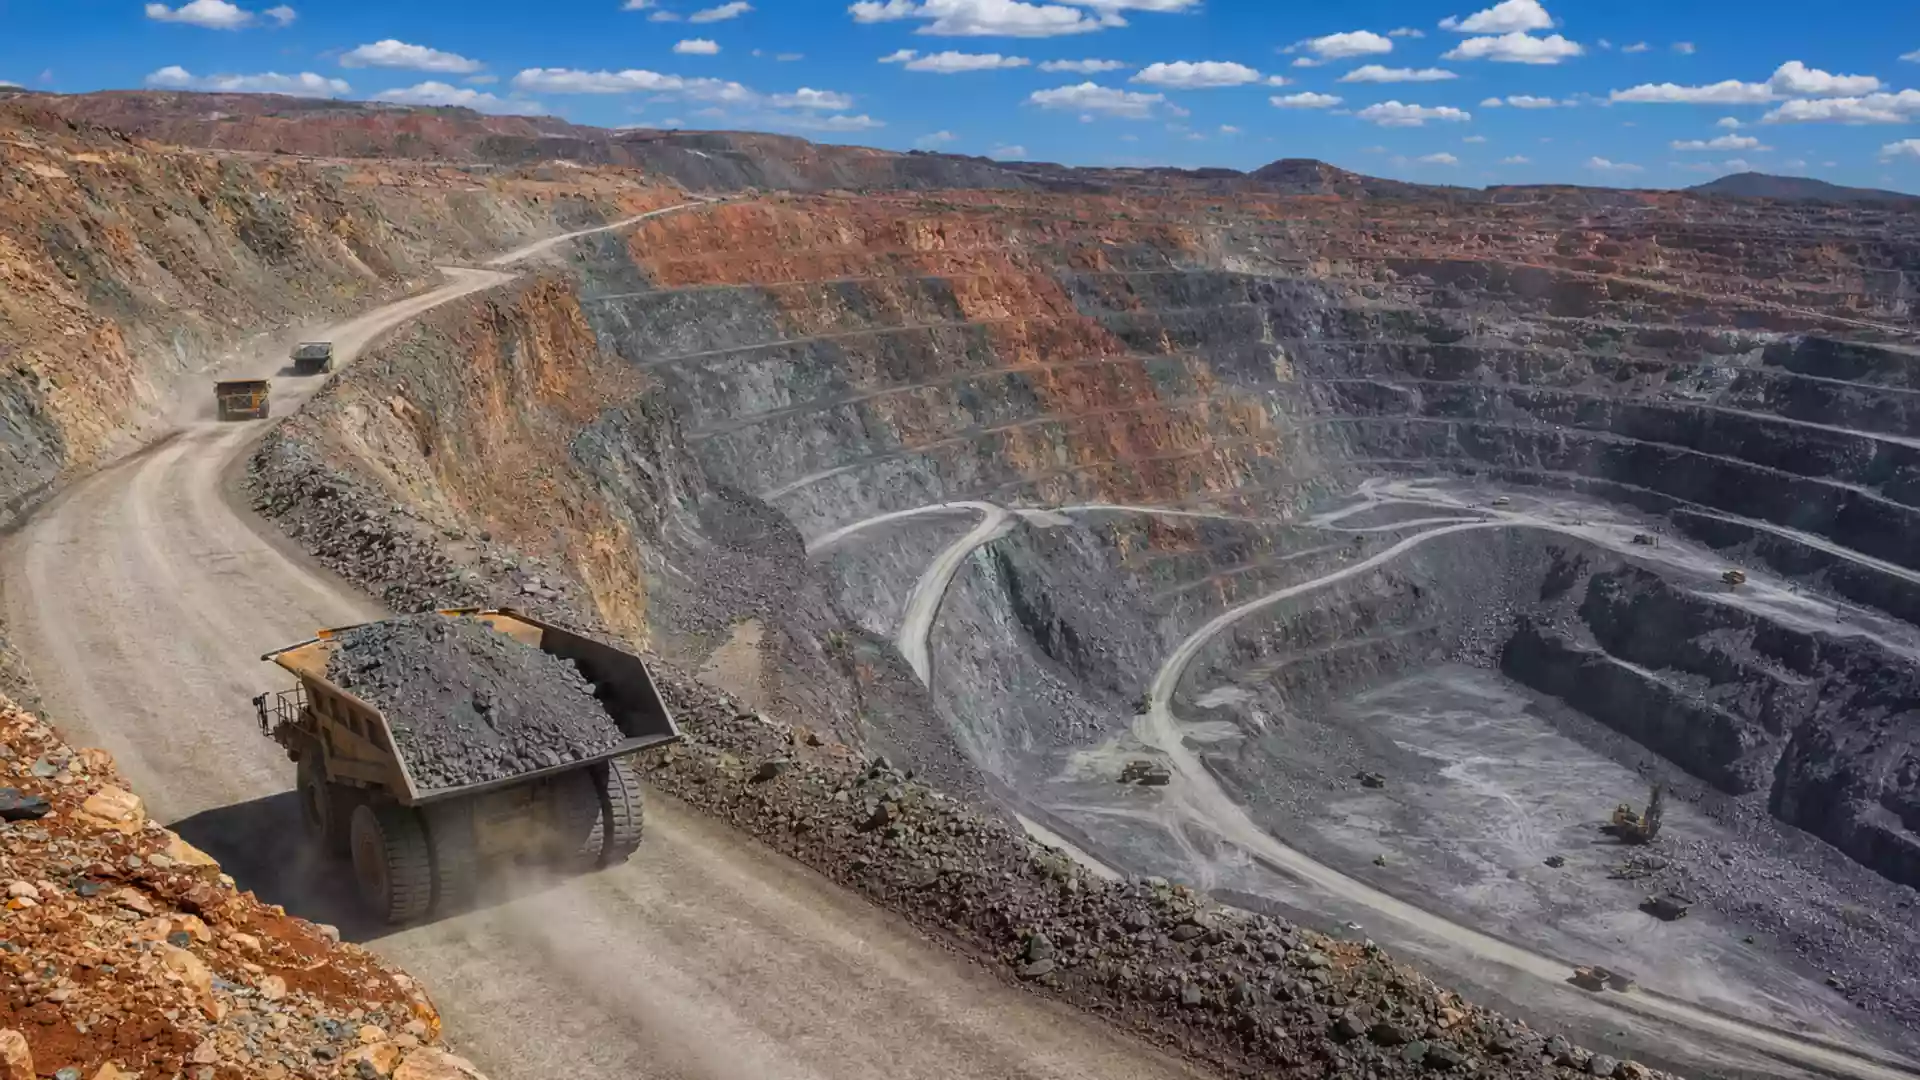
Start with the plant. Sangdong began round-the-clock operations on November 1, and ten hours later a technical failure brought it to a halt. The restart came two hours after that. A quick recovery points to a responsive team on the ground, but a reliable operation is a different matter from a fast fix, and the commissioning phase still demands technical work.
The filter press is the bottleneck
The clearest constraint sits at the filter press. According to Black, it processed 40 tonnes per hour against a design capacity of 80 tonnes per hour. Almonty has bought a used replacement press in Korea — a sensible response to a specific choke point, though its value will only be proven if throughput actually stabilizes. For shareholders, the test is the effect on operations, not the purchase itself.
Quality is moving in the right direction. Black said on Sunday that the finished product's grade was approaching 50%, up from the 40% cited in his previous circular. That signals progress in the ramp-up, provided the higher grade can be sustained. Pair a steadier throughput with consistent quality and the operating trajectory starts to look more convincing; quality strengthens the outlook, while dependable processing is what makes it hold.
Should investors sell immediately? Or is it worth buying Almonty?
Revenue growth raises the stakes
The business figures explain why execution carries so much weight. Media reports put Almonty's second-quarter 2026 revenue at C$43.0 million, a 498% increase year on year. That kind of growth makes what happens next especially important: future expansion, the report suggests, depends on maintaining throughput and recovery after the mine's first commercial shipment. A valuation anchored in production performance looks more appropriate than one that simply extrapolates past growth.
Then there is the dispute with Deutsche Rohstoff, which has quantified its claims while Almonty's counterclaims remain largely without a stated damages figure. In Canada, Deutsche Rohstoff is seeking roughly USD 67 million in total, comprising claims on 3.5 million conversion shares and the repayment of liabilities. According to Deutsche Rohstoff, about EUR 10 million is due and the fulfillment deadline has passed.
Two claims, two different obligations
The distinction matters for investors because the two categories create different obligations. The conversion-share claim centers on settlement in stock; the repayment claim concerns cash owed. Almonty benefits if it successfully fends off the demands, and carries exposure if Deutsche Rohstoff prevails on the liabilities. The headline total describes the scope of what is being claimed — assessing the financial consequences requires looking at each claim's basis and at how the courts rule.
Almonty, for its part, is demanding the return of shares tied to the 2014 sale of the Wolfram Camp Mine in Australia. The proceedings have been consolidated. Deutsche Rohstoff calls Almonty's allegations unfounded and largely time-barred — an assessment that comes from the opposing party. Almonty's own claims could carry economic weight if they succeed, but their significance is hard to gauge while the damages are mostly unquantified. Investors must weigh both the legal viability and the economic scale of the counterclaims.
The central question is what concrete obligation could emerge for Almonty from the dispute. A transparent quantification of the counterclaims, one that also reveals their basis, would make the situation easier to read. Relief would come from defeating the claims or prevailing on its own; a burden would arise to the extent repayments or delivery of the claimed conversion shares are enforced. Until then, the quantified demands and the open counterclaims deserve separate weight.
For now, the cautious read holds while Sangdong remains constrained by technical bottlenecks during commissioning. Improved product quality and a targeted fix for the filter press argue in Almonty's favor — if they translate into durably better operating performance. The next convincing step would be reliable throughput and stable quality working together. That is the standard against which confidence in Almonty's growth should be measured, and only when both hold does the positive outlook gain enough substance.
Ad
Almonty Stock: New Analysis - 12 November
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.