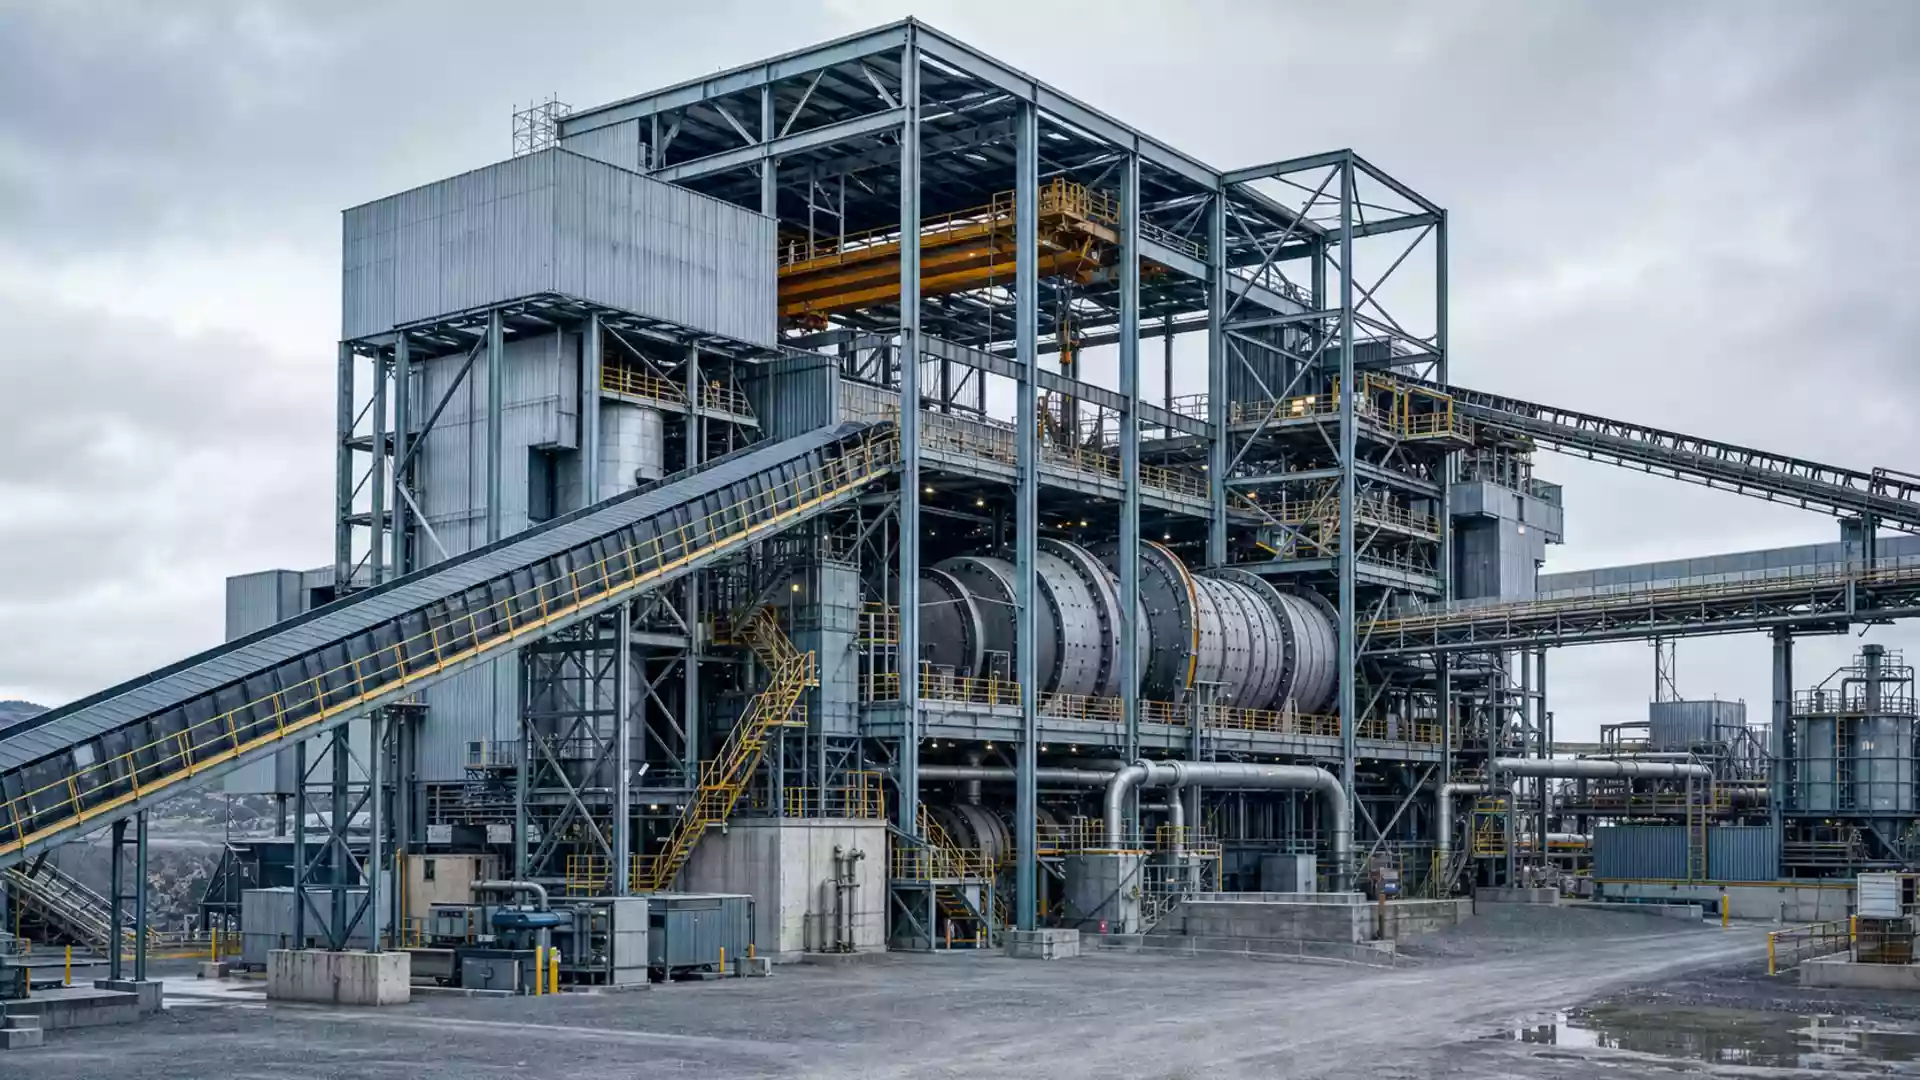
Almonty's Sangdong Mine Has a Buyer for Its Tungsten. What It Still Needs Is a Track Record.
Published on 11/17/2026 at 09:20 | Editorial boerse-global.de
A long-term offtake contract removes a chunk of uncertainty from Almonty's flagship project. It does not run a mine. That distinction sits at the heart of the current investment case: most of the output from Sangdong's first expansion stage is locked up with GTP for years to come, yet the market has no way of knowing when those commitments turn into steady shipments and dependable earnings.
Two analyst notes published yesterday frame that gap. Sphene Capital keeps its buy rating but trimmed its price target to USD 22.40, a level it applies over a 36-month horizon — a reminder that the bullish call is built for the long haul. B. Riley, meanwhile, expects Sangdong to contribute only marginally in the fourth quarter of 2026, with revenue arriving from the first quarter of 2027 and the first solid read on earnings power following in the second quarter of 2027.
Contracts Don't Run the Plant
Between a signed offtake and a verifiable earnings base sit several operational steps, and the unglamorous ones matter most. Sangdong has been running three shifts on a 23-hour schedule since the start of November. Before round-the-clock operation is possible, the water treatment system still needs adjusting. The first container left Busan after the quarter closed.
Shipping timing can shift the revenue contribution even while the mine is producing, which is why the long-term sales commitment and the short-term top line tell different halves of the same story. For investors, the question is whether a valuation rests on performance already visible or on performance still expected.
Should investors sell immediately? Or is it worth buying Almonty?
What the Third Quarter Actually Showed
The quarterly figures give those expectations an economic backdrop. In the third quarter of 2026, Almonty posted revenue of CAD 41.9 million and adjusted EBITDA of CAD 14.6 million, with stronger tungsten prices supporting the top line. B. Riley's forecast for adjusted operating profit before interest, taxes and depreciation in the fourth quarter of 2026 is USD 3.6 million — an analyst estimate, not a reported result, and a measure of how cautiously the near-term contribution is being pencilled in.
Long-term confidence in the project clearly does not mean its economic effect is already fully in hand. Higher tungsten prices lift the earnings prospects of existing operations, and Panasqueira is already benefiting from them. A favourable commodity market and a stable mine are two separate conditions, however; only their combination turns an attractive market opportunity into a durable business.
The Second Stage Comes With Strings
Sangdong's approved second expansion stage would lift processing capacity to as much as 1.2 million tonnes a year, with completion scheduled for 2027. The precondition is a stable first phase. Approval and a completion date are therefore no proof of correspondingly higher output — what counts is whether Almonty can ramp processing reliably while holding yields steady and keeping operating costs in check.
Sphene's list of proving points reads accordingly: a successful ramp-up of the first stage, stable yields and costs, confirmation of a changed Portuguese royalty regime, and progress on further projects. That royalty reduction is an expectation, not a secured relief, and should not be treated as one. September's first tungsten concentrate production and the commercial operating certificates issued the same month marked real progress, as did the first shipment loaded at Busan after quarter-end. None of it substitutes for evidence of sustained, stable operation.
Other Levers, Different Readiness
Beyond Sangdong, Sphene points to improved operating profitability at Panasqueira, liquidity from a placed convertible senior note, and extended offtake commitments. Additional production from Los Santos and Rwanda rounds out the development pipeline. These levers are not equal in maturity: the financing and the extended purchase obligations stand alongside expansion plans and regulatory expectations that have yet to be confirmed.
The larger arc is a transition from commodity opportunity to industrial reliability. Almonty holds long-term sales commitments and benefits from the price environment at Panasqueira. Whether that becomes a persistently convincing earnings base will be decided by yields, costs and regular deliveries — and that is where attention belongs.
Ad
Almonty Stock: New Analysis - 17 November
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.