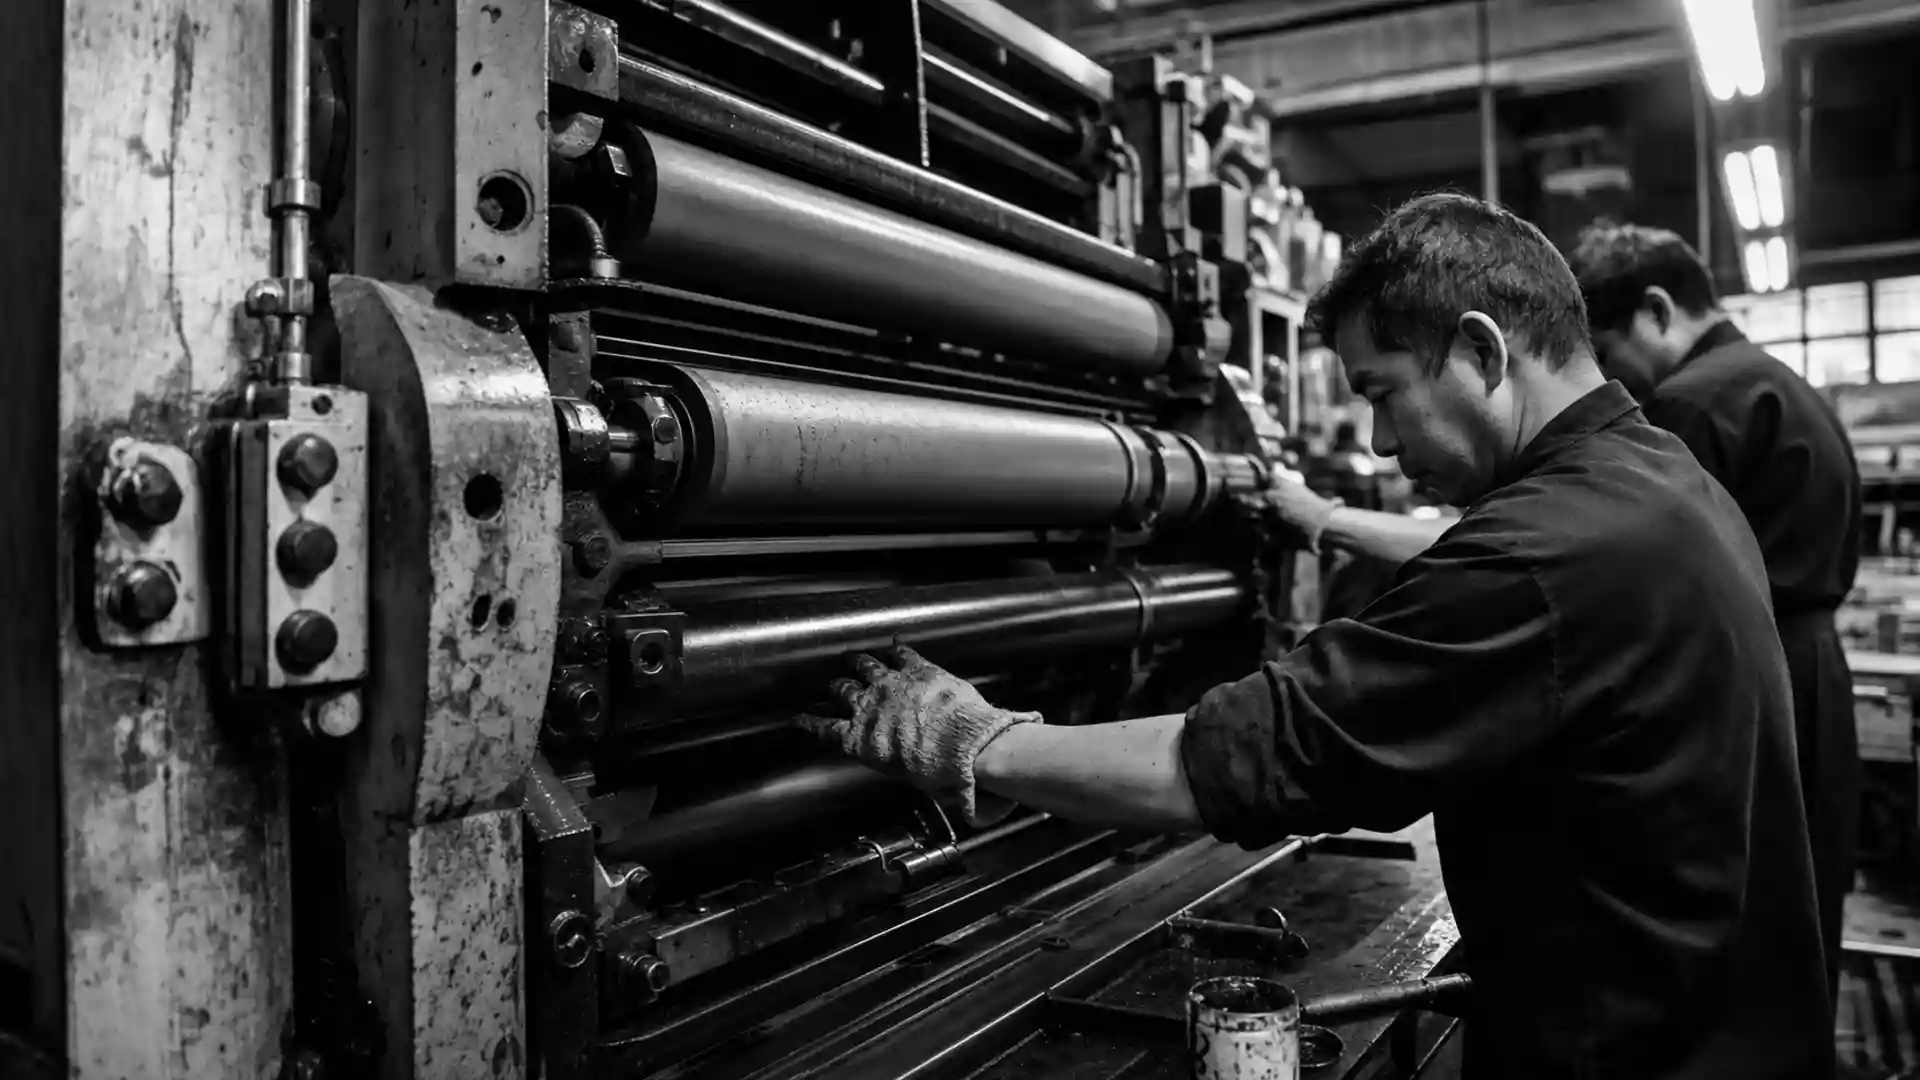
Heidelberg Druck's Cash Burn Doubles Even as Order Intake Picks Up
Published on 11/14/2026 at 14:11 | Editorial boerse-global.de
Heidelberger Druckmaschinen closed Friday's session down 3.2%, a move that lands squarely on a half-year report card showing thinner margins, lighter revenue and a free cash outflow that has widened sharply. The press maker's challenge is no longer simply selling machines — it is turning a fuller order book into profit and stemming the drain on its bank balance.
Orders offer the brighter side of the picture. Intake in the second quarter of fiscal 2026/2027 reached EUR 604 million, up from EUR 551 million a year earlier. Whether that translates into a genuine recovery depends on Heidelberg converting those bookings into profitable sales rather than simply shipping more volume at weaker prices.
Margins and Cash Both Move the Wrong Way
The clearest measure of the problem sits in the adjusted EBITDA margin, which slipped to 3.7% in the first half of 2026/27 from 6.4% a year ago. Revenue over the same period fell to EUR 913 million from EUR 985 million.
Management pointed to lower volumes, cost pressure and a deteriorating economic climate, particularly in the Middle East, alongside delays to technology projects. Negative product-mix effects added another layer of strain, making the quality of the remaining revenue — not just its headline level — the number that matters.
Should investors sell immediately? Or is it worth buying Heidelberger Druckmaschinen?
The cash line is starker still. Free cash flow came in at minus EUR 125 million for the half, roughly double the minus EUR 64 million recorded in the comparable period. A convincing turnaround would therefore need to show up in both the earnings statement and the cash flow statement, not one without the other.
Guidance Hinges on a Stronger Second Half
Heidelberg reaffirmed the outlook it had previously trimmed: broadly stable revenue for the full fiscal year 2026/2027 and an adjusted EBITDA margin of 5.6% to 6.6%. That band sits comfortably above the 3.7% achieved in the first six months, which means the forecast effectively bakes in a materially better second half.
Integration of manroland sheetfed is proceeding according to plan, according to the company, and a smooth continuation would give the recovery case a second leg to stand on alongside the improved order intake. The two would then reinforce each other: more orders, converted into revenue, lifting profitability.
Until that happens, the rebound remains conditional. Should order conversion fail to support the top line, the prospect of stable full-year revenue would weaken; should profitability stay stuck at current levels, the margin target would come under pressure regardless.
February 16 Becomes the Next Reckoning
Investors get their next hard data point on February 16, 2027, when Heidelberg has scheduled publication of its third-quarter 2026/2027 figures. That release will show whether the stronger order book is already feeding through to results.
For the recovery thesis to hold, execution and targets need to converge. A healthier order book on its own is worth little if the margin and the cash outflow do not follow it.
Ad
Heidelberger Druckmaschinen Stock: New Analysis - 14 November
Fresh Heidelberger Druckmaschinen information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.