Infineon's €20 Billion Question Meets a Wall of Trimmed Targets
Published on 11/19/2026 at 10:11 | Editorial boerse-global.de
Infineon shares finished Wednesday's session at €49.36, up 1.2%, and picked up further ground Thursday morning with a 2.9% advance as firmer sentiment across AI-related names lifted the sector. The immediate trigger came from Nvidia, whose revenue guidance landed ahead of expectations and, according to Reuters, eased worries about demand for AI chips. That industry backdrop matters for the mood. It does not, however, answer the question that actually governs Infineon's valuation: whether the company's own growth path holds up.
A €20 Billion Ambition Still Waiting for Proof
The number at the centre of the debate is roughly €20 billion in revenue targeted for fiscal 2027. Against the €16.353 billion Infineon booked in fiscal 2026, that implies a substantial step-up — but it remains a forecast, not a delivered result. Investors are therefore weighing whether to extend credit to the target now or to hold out for harder evidence. The segment result margin is pencilled in at the mid-20% range.
What would help is detail on how the planned expansion translates into actual corporate planning. Fresh elaboration on that front would make the trajectory easier to verify; a friendlier tone from the wider industry, on its own, will not settle the matter.
Brokers Keep the Faith but Cut Their Numbers
Support for the bullish case is not in short supply, though it has become more measured. Bernstein Research reaffirmed its "Outperform" rating on Tuesday with a price target of €82 — a supportive voice, but a confirmation rather than a fresh upgrade, and best read as an existing view rather than a new catalyst.
Should investors sell immediately? Or is it worth buying Infineon?
Others have been busy sharpening their pencils. Deutsche Bank Research trimmed its target on 12 November from €85 to €75 while keeping its "Buy" rating. Jefferies cut its own from €96 to €74 the day before, also sticking with "Buy" and attributing the move to the sector's recent de-rating. A third house lowered its target to €80, again with a purchase recommendation intact. The pattern is clear: conviction on the stock has survived, but the numbers attached to it have come down.
Buyback Is for Employees, Not for Yield Hunters
Infineon's capital return programme has been running since 11 November and will wrap up no later than 27 November. The company disclosed on Monday that it had already repurchased 2,397,524 of its own shares, with the purchases executed between 11 and 13 November. In total, up to seven million shares may be bought back for a maximum aggregate outlay of €450 million.
The purpose is explicitly tied to servicing existing employee participation programmes. That is a clearly defined use, and anyone reading an extra distribution thesis into the measure would be going beyond the announced terms. On the growth question, the buyback offers no independent answer.
Silicon Carbide Milestone Adds a Technical Data Point
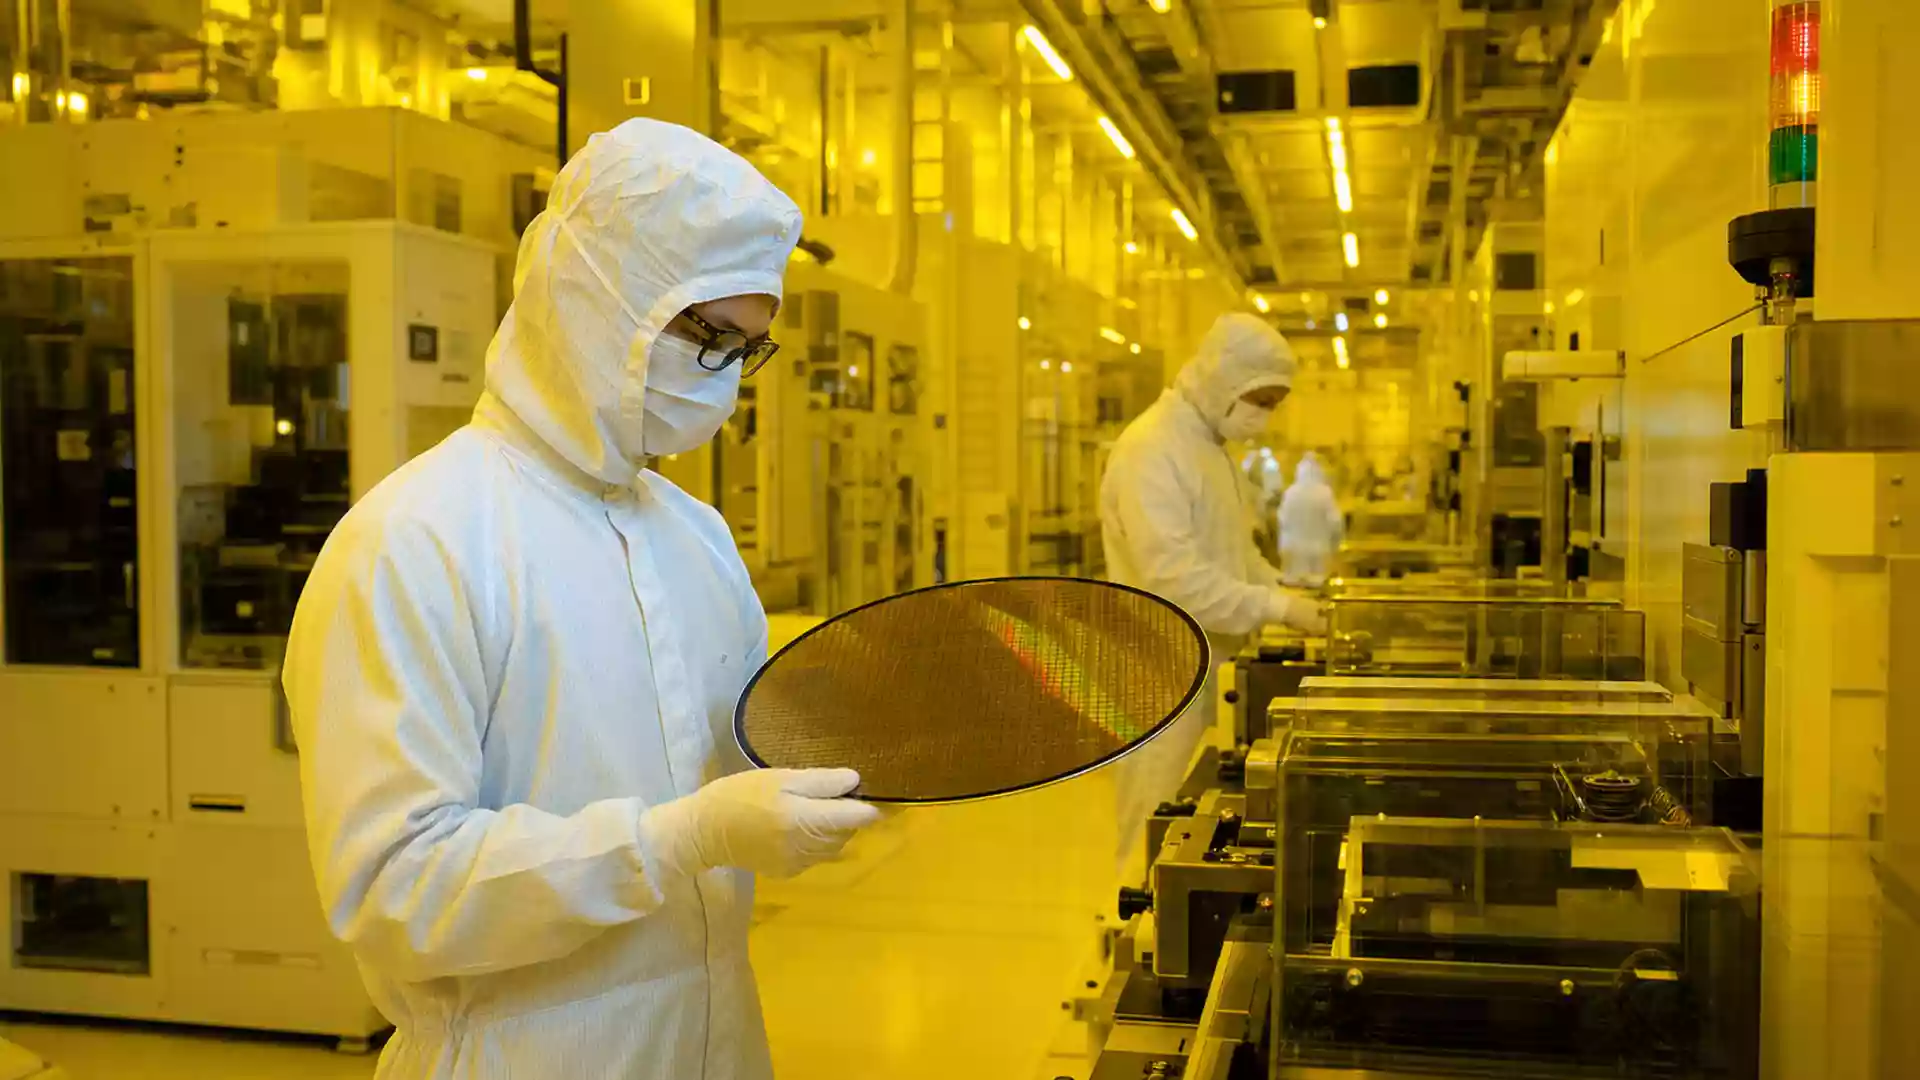
Operational progress offers a separate thread of support. On 9 November, Infineon reported that it had processed functional power devices on 300-millimetre silicon carbide wafers at its Villach site. According to the company, the achievement demonstrates the feasibility of SiC processing on that wafer format — a concrete technological step. What matters for the investment case beyond that is how such developments eventually feed through to the business.
Infineon at a turning point? This analysis reveals what investors need to know now.
Conference Circuit Becomes the Proving Ground
The near-term test comes at the Morgan Stanley TMT Conference in Barcelona, running today and tomorrow. Attendance alone says nothing new about operating performance; a sharpening of the business outlook would. After that, the virtual Barclays Sustainable Future Forum on 24 November and the Goldman Sachs European AI and Semis Symposium in London on 24–25 November offer further platforms.
The bear case is equally straightforward. If additional commentary stays vague, investors must keep trusting that the existing guidance will be met — and a disappointment on expected growth could then weigh more heavily than cheerful industry headlines. The risk sits in the gap between announced ambition and demonstrated delivery. Should Infineon reaffirm its revenue outlook and back it up convincingly, the positive growth scenario stays intact and attention can shift toward the company's own execution rather than a supportive climate for AI-linked stocks. Should the expected expansion be called into question, assumptions will need revisiting. What counts is what management says about the business — not how many appearances fill the calendar.
Ad
Infineon Stock: New Analysis - 19 November
Fresh Infineon information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.