Metallium Faces a 42% Pay Revolt While Gator Point Holds the Revenue Key
Published on 11/14/2026 at 16:31 | Editorial boerse-global.de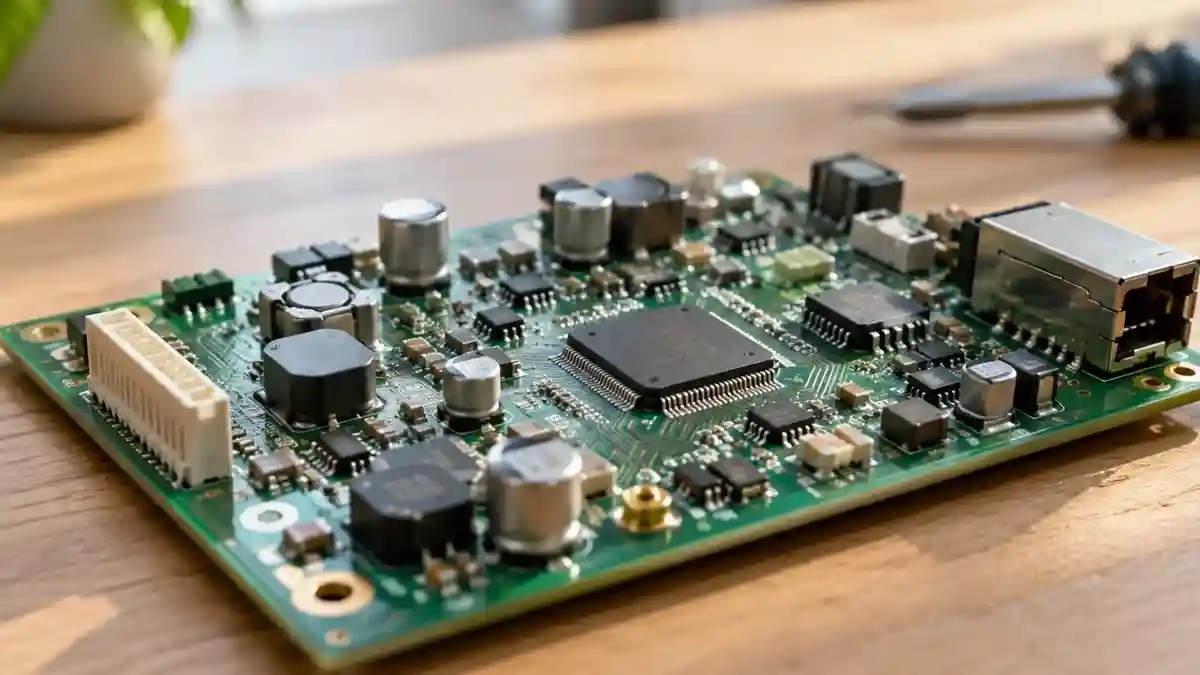
Metallium's annual general meeting delivered a split verdict on Tuesday: shareholders waved through every resolution put to a vote, yet handed management a "first strike" under Australian law over its remuneration report. According to company figures, 41.71% of votes cast on the report were opposed — comfortably past the 25% threshold that triggers the designation. The rejection did not block adoption of the report, but it left a mark.
Items 4 and 10(e) never reached a ballot, having been withdrawn beforehand, so no decision was recorded on them. Everything else carried.
Board points to a hostile backdrop
In his address, the chief executive flagged economic and geopolitical uncertainty weighing on the willingness to invest in both emerging technologies and the critical metals sector. That was a sector-wide observation, not an explanation for any single day's share price action. The stock itself advanced 2.6% on Friday.
Recovery rates above 90% — provisional
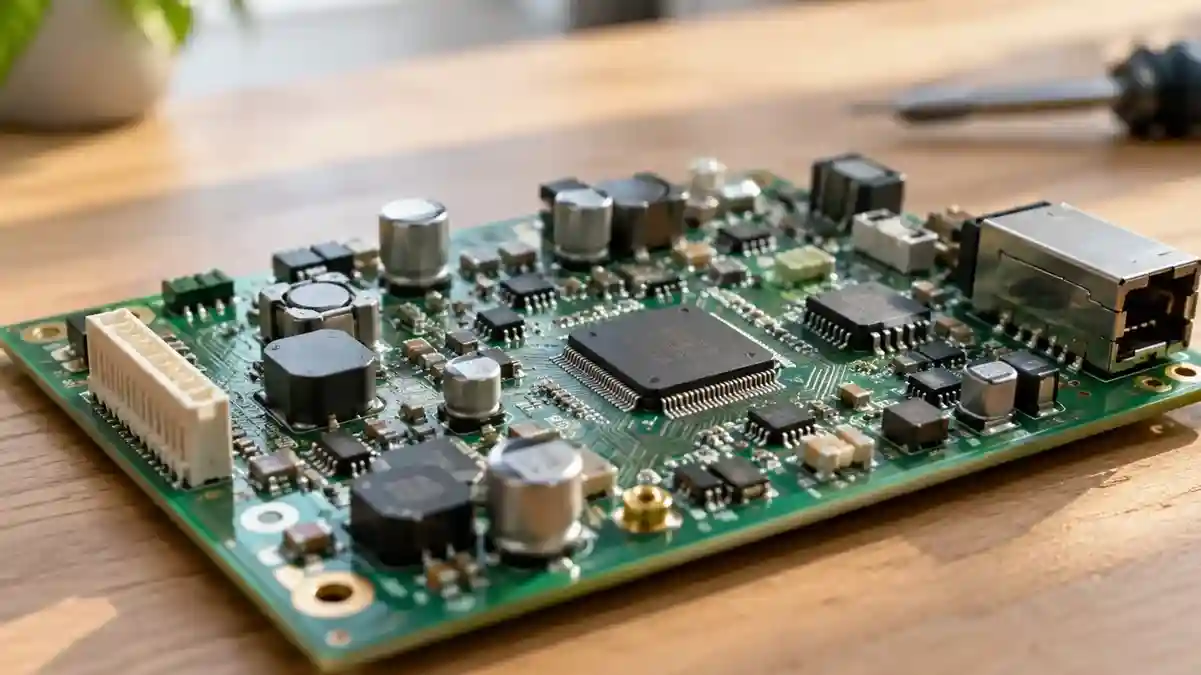
The operational centrepiece of the meeting was a set of preliminary tests on printed circuit board pre-treatment. Metallium reported recovery rates exceeding 90% for copper, gold, silver, tin and palladium, with the metals arriving in mixed metal-bearing streams. The company is explicit that these are provisional results: further validation of the findings and qualification of the products are both still running.
Should investors sell immediately? Or is it worth buying Metallium?
That caveat matters more than the headline number. For investors, the question is whether promising processing results can be converted into products Metallium can actually sell.
Gator Point runs on a staged sequence
Attention now fixes on Gator Point, where the company intends to install, commission and operate PCB processing in stages during the first half of 2027. Metallium told shareholders it expects initial revenue from the corresponding metal products within that same window.
Each link in that chain has to hold. Installation progress would count as an operational milestone; revenue, however, requires a successful commissioning and then steady operation on top of it. The further the sequence carries, the firmer the case for the announced market entry becomes.
Where the thesis could slip
The counterargument sits in the work still outstanding. As long as validation and product qualification drag on, the commercial side remains tethered to technical preconditions. Extra testing could push first revenue further out even if installation stays on schedule. A delay at commissioning would in turn weigh on the operating phase — and, for shareholders, on the timing of the expected first product sales.
Management's remarks on market uncertainty sharpen rather than soften that test. In a climate that has dampened appetite for emerging technology and critical metals names, verifiable operational progress carries more weight than projections. The positive case gains traction only as results along the chain accumulate.
Metallium at a turning point? This analysis reveals what investors need to know now.
First half of 2027 is the yardstick
That half-year is the next hard operational marker: staged plant ramp-up plus first revenue from PCB metal products. Should validation keep advancing and the schedule hold, the revenue outlook remains the central plank of the bull case. Should qualification stall or operations slip, the timeline underpinning that view weakens.
What settles the argument is the combination — successful qualification, continuous processing and initial product revenue, all inside the promised window.
Ad
Metallium Stock: New Analysis - 14 November
Fresh Metallium information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.