
Nvidia Halts H200 Production for China as Insiders Trim Stakes and Credit Hedging Surges
Published on 09/24/2026 at 07:50 | Editorial boerse-global.de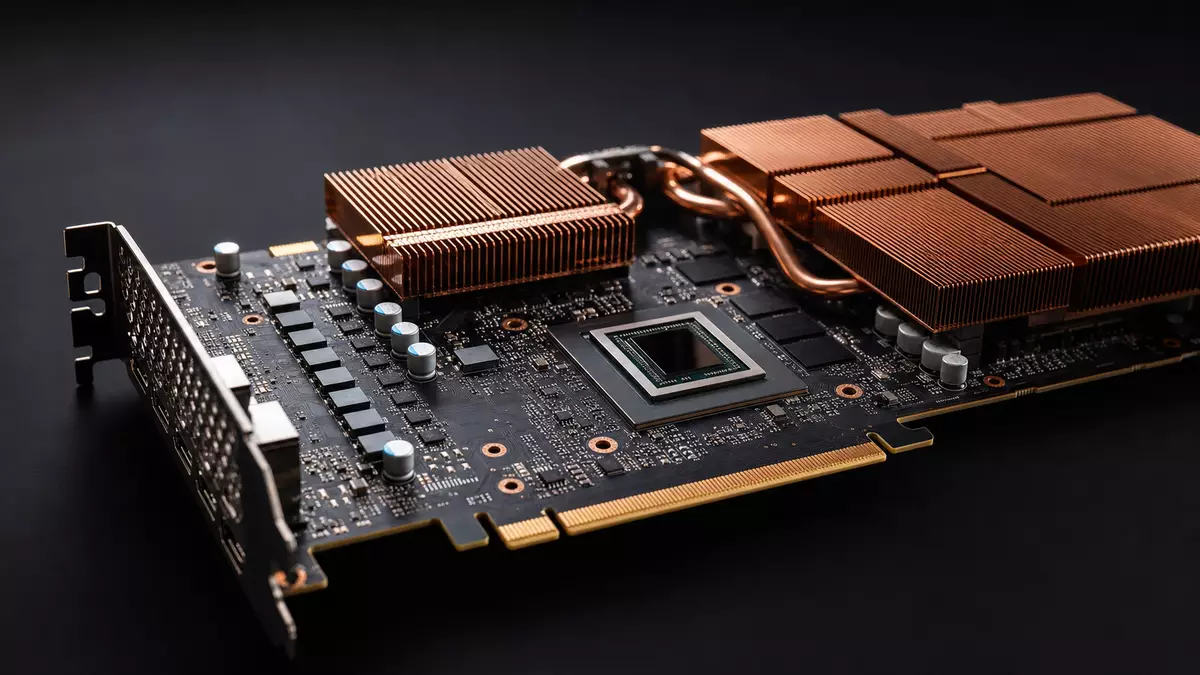
Nvidia is quietly redrawing its manufacturing map. According to Financial Times reports, the chipmaker has stopped production of its H200 models built specifically for the Chinese market, redirecting the entire output of contract manufacturer TSMC toward its next-generation Vera Rubin architecture rather than tying up capacity with export-restricted silicon.
The logic behind the pivot is straightforward. With US regulations choking off shipments to the Far East and data-center revenue from China effectively penciled in at zero, management is placing its chips on technological leadership instead of chasing a market it can no longer reliably serve. The complexity of running a global business, in other words, demands an uncompromising bet on the next system architecture.
That decision lands against a backdrop of growing caution on multiple fronts. Corporate insiders have been converting shares into cash at scale, and while CFO Colette Kress and chief legal officer Timothy Teter both acted through pre-arranged selling plans — standard wealth-management practice at technology firms — the sheer volume of the transactions carries a psychological weight for shareholders. Are even the people with the clearest view of the order book starting to question how much further the steep valuation can run?
Hedging Activity Picks Up in Credit Markets
The skepticism is not confined to equity trading. In bond markets, a parallel shift is unfolding that retail investors often miss: protection against Nvidia credit defaults has become one of the most heavily traded instruments in the credit-derivatives segment in recent months. Analysts at Barclays describe it as an unprecedented wave of hedging activity tied to artificial intelligence.
Meanwhile, the company is doing more than shipping accelerator cards to data centers. It is assembling a monolithic ecosystem layer by layer, binding developers, algorithms and future computing architectures to its own platform. Its market capitalization of EUR 4,691.32 billion puts it in territory that once seemed unthinkable. On Wednesday the stock slipped 1.1 percent to EUR 197.76, though such daily swings barely touch the fundamental story.
Should investors sell immediately? Or is it worth buying Nvidia?
Hugging Face and the Grip on Developers
The real repositioning is happening away from the ticker. Nvidia is extending its lead not through silicon alone but through targeted access to the infrastructure of the global developer community. Hugging Face is widely regarded as the epicenter for freely accessible AI models, libraries and training data — and whoever controls that hub sits directly at the source of future software development.
That transforms a pure chipmaker into the operator of AI's central workbench. Developers building or fine-tuning models will move even more seamlessly within Nvidia's architecture, minimizing the risk of customers drifting to rival hardware platforms. Hardware becomes merely the foundation for a broader software universe.
A Bridge Into the Quantum Era
Management is already looking well past today's supercomputers. On September 14, the company announced an expansion of its open-source CUDA-Q platform with an orchestration layer called CUDA-Q Logical, designed to give developers a programmable, verifiable approach to building applications for fault-tolerant quantum computers.
That this is not distant future music was demonstrated by the renowned Fermilab, which used CUDA-Q Logical to cut development time for fault-tolerant architectures from five months to just three weeks. Can a company defend its moat more effectively than by writing the operating system for the technologies of the decade after next? Nvidia is securing the interfaces of the quantum era before commercial quantum processors are even broadly deployable.
Financial Firepower Underwrites the Expansion
Such an expansive architecture strategy can only be financed with unprecedented financial firepower. In its second fiscal quarter, which ended July 26, Nvidia generated revenue of USD 96.2 billion — an 18 percent increase over the prior quarter and a 106 percent jump year over year. For the current quarter, the company has guided toward USD 108.0 billion in revenue, with a projected GAAP and non-GAAP gross margin of 74.0 percent.
For investors, this structural shift means a new valuation lens. Anyone who views Nvidia primarily as a cyclical chipmaker overlooks the speed at which the company is making its platform irreplaceable. As long as it manages to chain both today's AI workflows and tomorrow's quantum structures to its own software, the tech giant keeps the threads of the entire industry firmly in hand.
The market is already registering the mix of profit-taking, derivatives hedging and geopolitical adjustment. In German trading yesterday, the stock gave up 0.9 percent to EUR 198.10. Despite the recent consolidation, the paper sits just 2.2 percent below its 52-week high of EUR 202.50. The phase of unchecked euphoria is giving way to one of sharper differentiation — and even the makers of the hardware are bracing for rougher winds.
Ad
Nvidia Stock: New Analysis - 24 September
Fresh Nvidia information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


