
Rheinmetall's €80 Billion Backlog Tested by Delays and a Chastened Market
Published on 09/26/2026 at 12:01 | Editorial boerse-global.de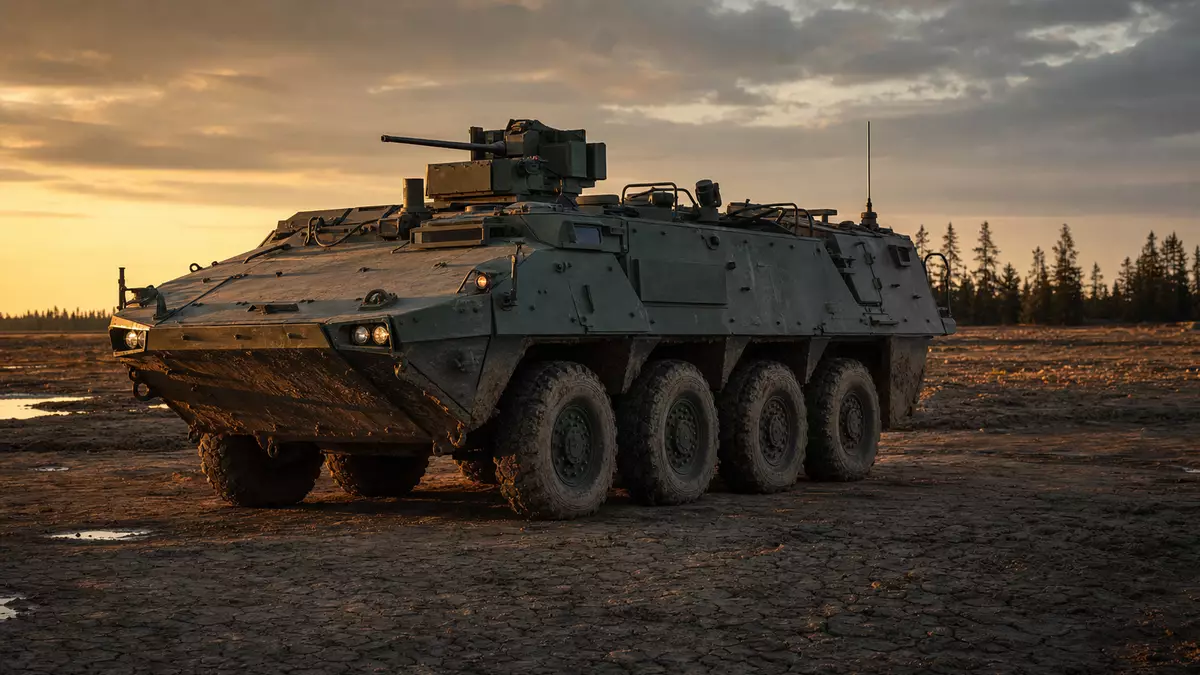
Rheinmetall finds itself navigating a widening gap between the demand it has captured and its ability to convert that demand into delivered hardware. The Düsseldorf-based defence group has amassed an order book exceeding €80 billion, yet operational friction at the project level is drawing scrutiny from investors who had grown accustomed to a steady stream of contract wins.
Shares in the MDAX- and DAX-listed company closed Friday at €986.60, a daily decline of 0.9%. Since the turn of the year, the stock has shed 36% of its value, reflecting a broader pullback in European defence names. Media reports pointed to geopolitical debates and speculation about possible diplomatic negotiations in the Ukraine war as weighing on the sector, with peers such as Renk and Hensoldt also coming under selling pressure. Market watchers cited not only signals of potential talks but also mounting uncertainty over the future shape of Western defence budgets.
Execution Stumbles Come Into Focus
The softer sentiment has coincided with concrete industrial setbacks. Rheinmetall has guided toward a significantly negative operating free cash flow for the current financial year. Delivery of the Skyranger 30 air-defence system is now expected to slip by roughly a full year, from mid-2026 to mid-2027. More consequential still are problems with the Schwerer Waffenträger Infanterie programme, encompassing 123 wheeled vehicles with a total volume of €2.7 billion. That project faces a delay of at least eleven months against the original contract, stemming from insufficient maturity and quality shortcomings. Questions over possible defects in protective plating have added to the pressure, casting a shadow over the German defence sector more broadly.
Should investors sell immediately? Or is it worth buying Rheinmetall?
Analysts Keep the Faith
Despite the recent weakness, sell-side analysts have held their ground. Berenberg reaffirmed its buy rating on the stock with a price target of €1,600, arguing that the fundamental potential of the defence contractor remains intact through the current market swings. Bernstein had already confirmed an "outperform" rating with a €1,900 target on Monday. Both houses point to the company's still-brimming order books and the long-term modernisation requirements of European armed forces as reasons to expect substantial upside from present valuation levels.
Contract Wins Keep Rolling In
Away from the share-price turbulence, Rheinmetall continues to advance its project pipeline. Trials of maritime surveillance systems took place during a NATO exercise in Portugal, and on Wednesday the group's Naval Systems division secured a multi-year framework agreement from the Generalzolldirektion for the maintenance of four new LNG customs vessels. That follows a summer of significant new business: a share of just under €1 billion in the Omnia Training consortium for British combat training, and modernisation work on the frigate BAYERN for the German Navy in a project valued in the mid-three-digit millions of euros. Management is pressing ahead with operational execution of its defence and technology programmes as planned.
How quickly the company resolves its quality issues and clears the path to timely delivery on its major contracts will shape the narrative in the months ahead.
Ad
Rheinmetall Stock: New Analysis - 26 September
Fresh Rheinmetall information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


