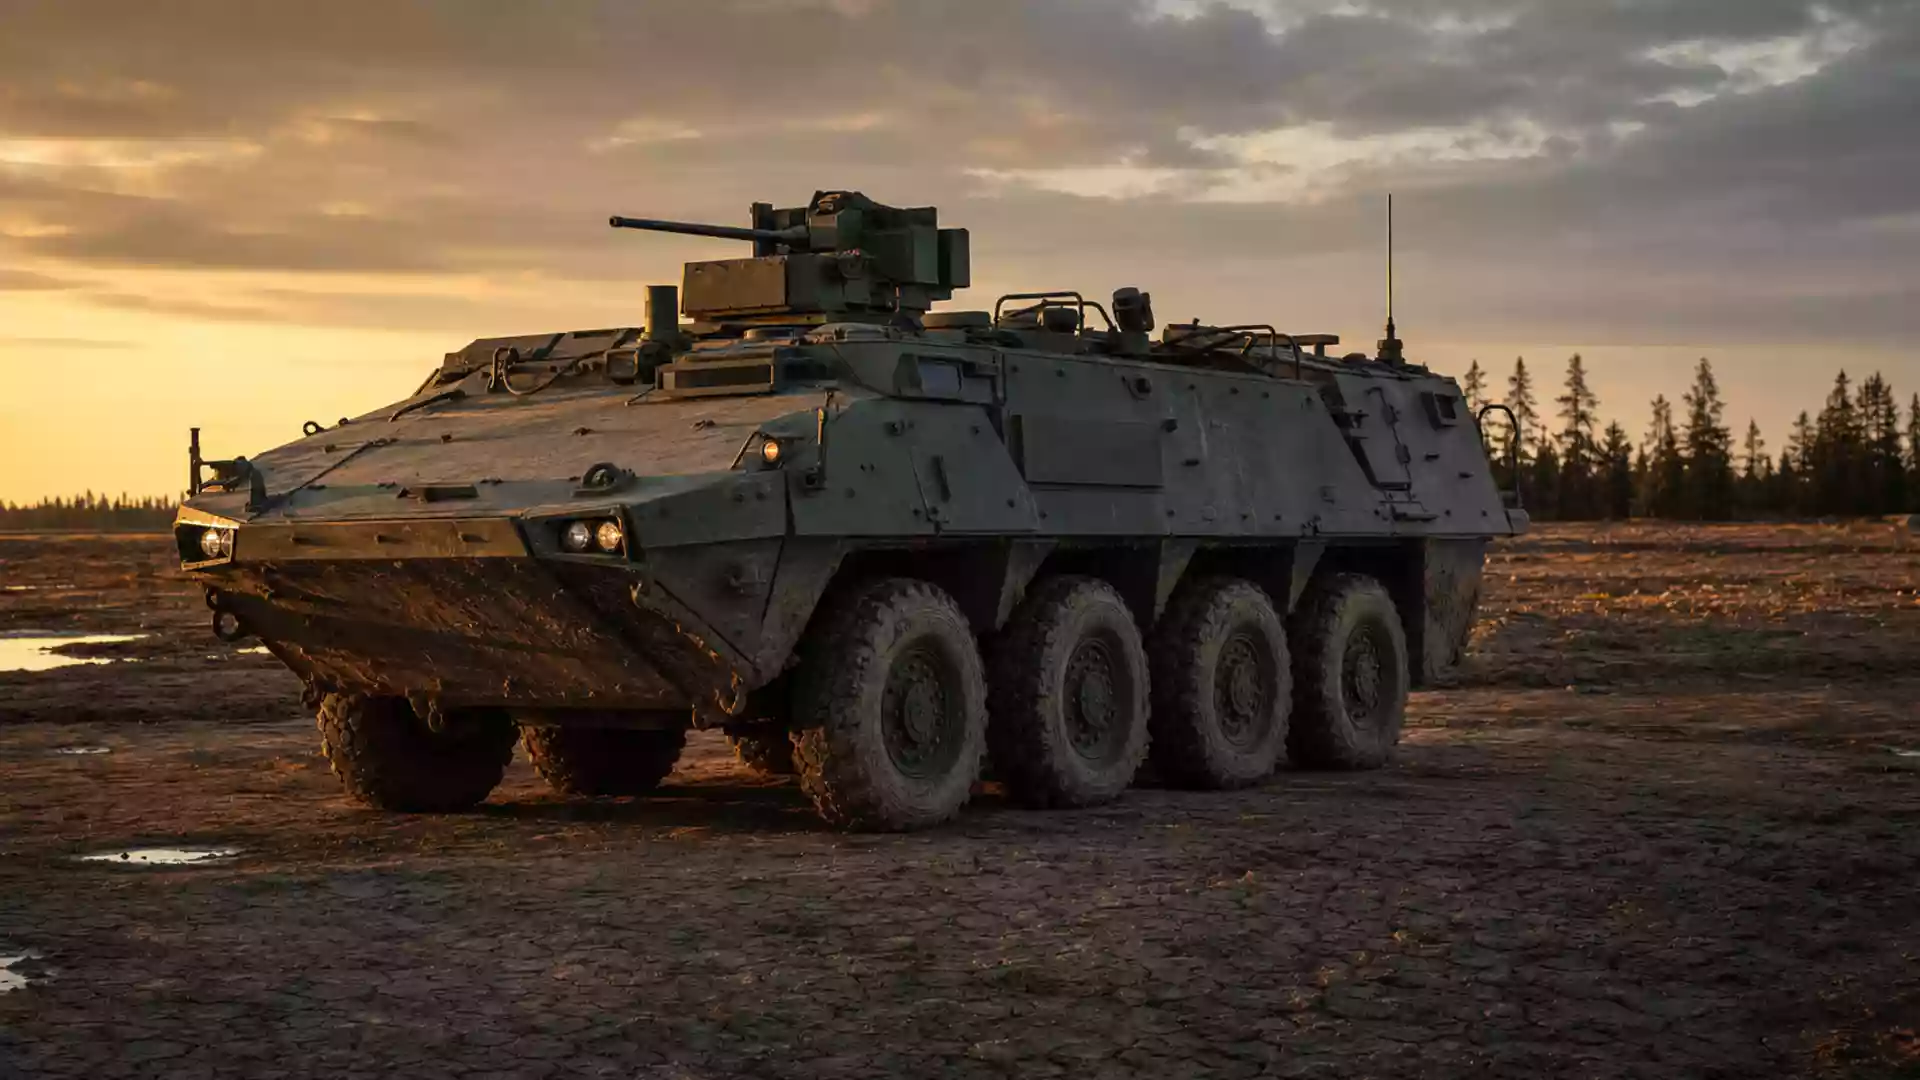
Rheinmetall's Margin Math: CSG's Warning Exposes the Price Side of the Defence Story
Published on 11/12/2026 at 04:51 | Editorial boerse-global.de
Rheinmetall shares fell 6.3% on Wednesday, with a second reading putting the decline at 6.8%, as a profit warning from Czech defence group CSG rippled through the sector and sharpened questions about ammunition pricing across the industry.
CSG, citing Reuters, cut its guidance for the operating EBIT margin to roughly 21%, a reduction that followed weak quarterly figures. The company attributed the downgrade to falling prices for conventional artillery shells — a risk that goes beyond the timing of individual orders. Weaker selling prices can erode earnings power even when volumes keep growing.
For Rheinmetall, those sector-wide concerns land on top of targets the company had already trimmed. Investors weighing a recovery now have to balance two separate forces: delayed orders that could still contribute to revenue later, and sustained price pressure that would call into question the underlying quality of the business.
The Operating Margin Becomes the Yardstick
The number that matters most is the operating margin. Alongside its third-quarter 2026 report, Rheinmetall cut its full-year target for the figure to 18.5%, down from around 19%. That level now serves as the benchmark for whether the group can absorb its recent setbacks within its revised plan.
Should investors sell immediately? Or is it worth buying Rheinmetall?
The cause of the earlier correction is central to how the stock should be read. Rheinmetall pointed to delays on the Bundeswehr's Arminius project and on lot acceptances for artillery ammunition. The Arminius order is now expected in 2027. Such slippage affects the timing of revenue first; falling ammunition prices could additionally weigh on how profitable that revenue turns out to be.
Revenue guidance for 2026 was reduced to about EUR 13.2 billion, against a prior range of EUR 13.7 billion to EUR 14.2 billion.
Any stabilization of the investment case would require the lower plan to be robust enough to absorb both the delays and the pricing risk. A further deterioration would raise the question of whether the adjustment has already gone far enough.
A Belgian Order as the Counterweight
On the positive side of the ledger sits the Belgian contract announced on Monday. Rheinmetall is to supply 20 Skyranger 30 air-defence systems, with the order for systems and logistics valued in the mid-three-digit millions of euros, according to company statements.
That deal offers a concrete counterpoint to the anxiety around the artillery business. It would prove especially valuable if Rheinmetall delivers such orders on schedule and converts them reliably into earnings — shifting the debate toward operational execution rather than further guidance cuts.
The existing growth record belongs in the same column. In the first nine months of 2026, revenue reached EUR 8,376 million, up 38%.
The recovery case therefore rests on demonstrated growth and firm orders. It gains credibility to the extent that this business base can carry the revised earnings plan. The decisive test lies in execution and the profitability achieved along the way.
Two Brokers Move to the Same Target
Skepticism found support on Monday from Bank of America. The bank downgraded Rheinmetall from "Buy" to "Neutral" and cut its price target from EUR 1,300 to EUR 900, citing lower expected momentum in artillery and armoured vehicles as well as pricing risks.
That assessment goes to the heart of the bear case. If weaker momentum and lower prices arrive together, the operating margin could come under heavier strain. Additional orders would then improve the outlook mainly if their execution stays sufficiently profitable.
Rheinmetall at a turning point? This analysis reveals what investors need to know now.
Berenberg followed on Tuesday, trimming its target from EUR 1,020 to EUR 900 while keeping a "Hold" rating. Analyst George McWhirter pointed to execution risks and uncertainty over how predictable demand will be. Both moves point to a more cautious valuation of the stock.
For investors, a stabilization of business expectations would matter more than a simple reference to long-term order opportunities. The risk is that sector-wide concerns feed through into further revisions of earnings assumptions.
What the Capital Markets Day Must Deliver
As long as the revised margin plan holds and new orders are executed reliably, a recovery scenario remains defensible. If price pressure intensifies and weighs further on expected profitability, the cautious view would gain the upper hand.
The next fixed date is the capital markets day scheduled for 27 November. For the investment decision, what will matter most are statements on the durability of the targets and on operational delivery. A more convincing outlook would emerge if Rheinmetall can credibly set out how the plan remains achievable even under tougher pricing conditions.
Ad
Rheinmetall Stock: New Analysis - 12 November
Fresh Rheinmetall information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.